IOSS lets you declare and pay import VAT on distance sales of goods into the EU in consignments not exceeding EUR 150. This page is general information, not tax advice.
The route, stop by stop
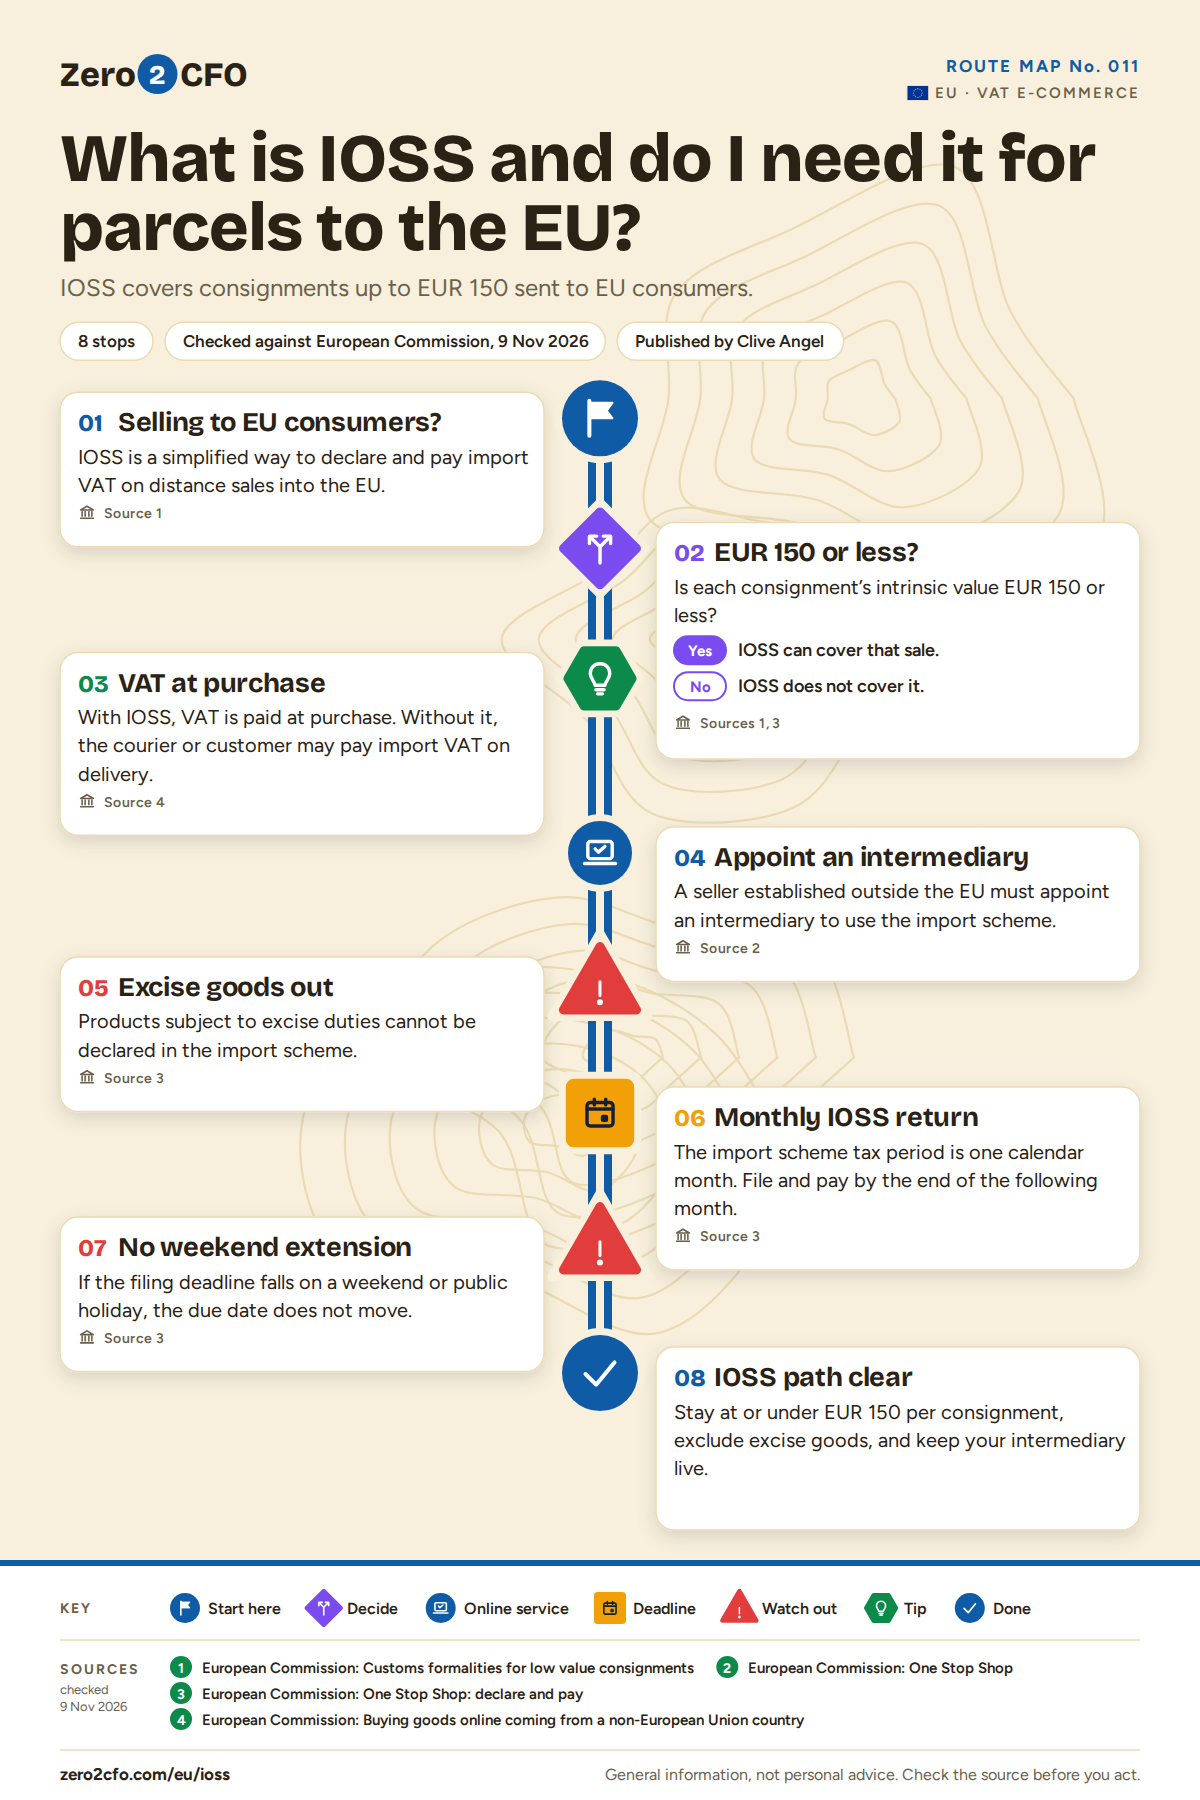
01Selling to EU consumers?
IOSS is a simplified way to declare and pay import VAT on distance sales into the EU.
Source 1
03VAT at purchase
With IOSS, VAT is paid at purchase. Without it, the courier or customer may pay import VAT on delivery.
Source 4
04Appoint an intermediary
A seller established outside the EU must appoint an intermediary to use the import scheme.
Source 2
05Excise goods out
Products subject to excise duties cannot be declared in the import scheme.
Source 3
06Monthly IOSS return
The import scheme tax period is one calendar month. File and pay by the end of the following month.
Source 3
07No weekend extension
If the filing deadline falls on a weekend or public holiday, the due date does not move.
Source 3
08IOSS path clear
Stay at or under EUR 150 per consignment, exclude excise goods, and keep your intermediary live.
The EUR 150 limit
The Commission’s low value consignments rules set the IOSS threshold at consignments not exceeding EUR 150.
Why use IOSS
With IOSS, VAT is paid at the point of purchase on the website. Without it, import VAT may be charged to the consumer on delivery, and goods can be held pending payment of duty and tax.
Sellers outside the EU need an intermediary
A taxable person established outside the EU is required to appoint an intermediary to use the import scheme.
Excise goods are out
Products subject to excise duties cannot be declared in the import scheme.
Monthly return
The import scheme tax period is one calendar month. The return and payment are due by the end of the following month, with no weekend or public holiday extension.
Common questions
Is the threshold in pounds?
No. The EU sets the limit in euros: EUR 150 per consignment.
Do I need an intermediary from Great Britain?
Yes, if you are established outside the EU and choose to use IOSS.
Is this tax advice?
No. It is general information from Commission pages checked on 9 November 2026. Rules change, so check the sources before you act.
Where the rules come from
- European Commission: Customs formalities for low value consignments checked 9 November 2026
- European Commission: One Stop Shop checked 9 November 2026
- European Commission: One Stop Shop: declare and pay checked 9 November 2026
- European Commission: Buying goods online coming from a non-European Union country checked 9 November 2026
This map is general information, not personal advice. Rules and rates change, so check the sources before you act. If your situation is tricky, talk to your accountant or tax adviser.