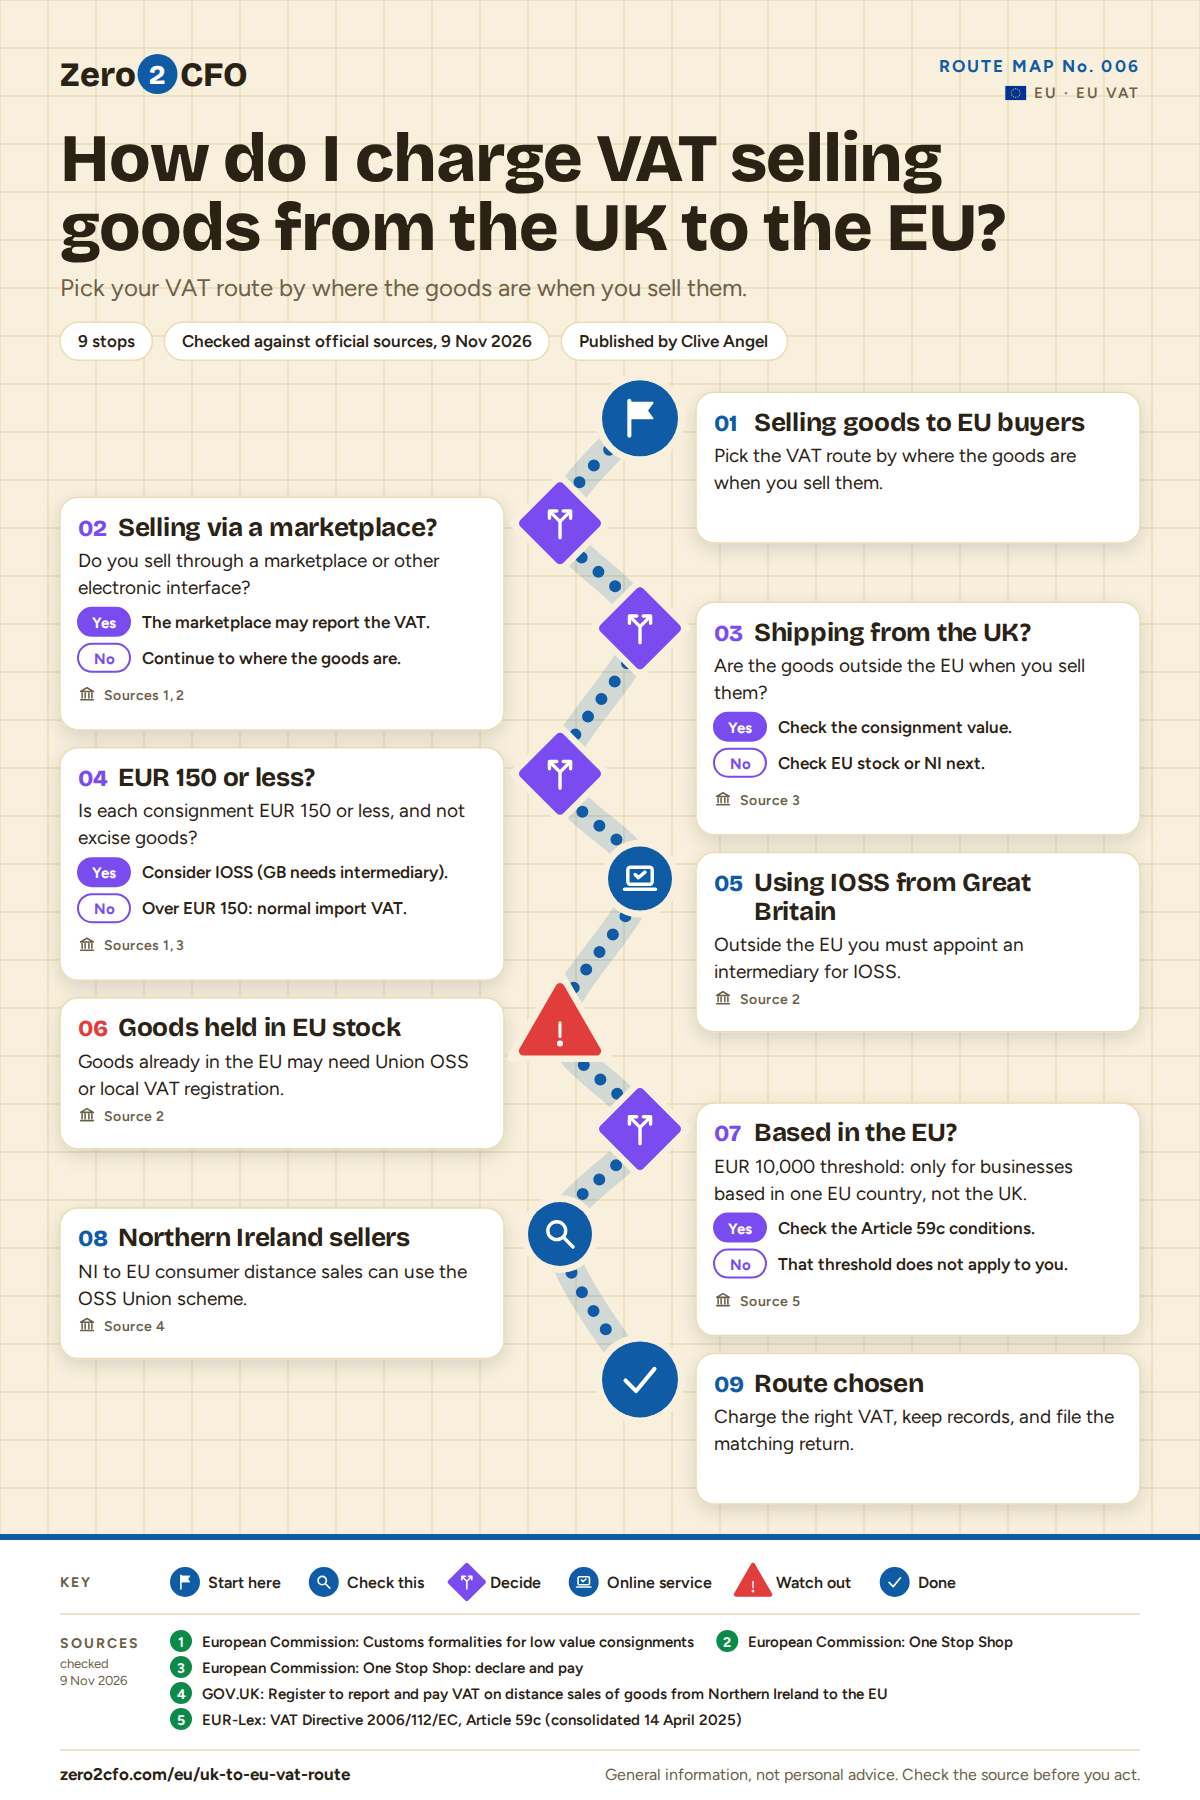
If you sell goods from the UK to consumers in the EU, start with the marketplace test, then ask where the goods are when you sell them. Great Britain sellers who use IOSS must appoint an intermediary. Excise goods are out of IOSS. The EUR 10,000 threshold only applies to businesses based in one EU country. This page is general information, not tax advice.
The route, stop by stop
01Selling goods to EU buyers
Pick the VAT route by where the goods are when you sell them.
03Shipping from the UK?
Are the goods outside the EU when you sell them?
YesCheck the consignment value.NoCheck EU stock or NI next.Source 3
06Goods held in EU stock
Goods already in the EU may need Union OSS or local VAT registration.
Source 2
07Based in the EU?
EUR 10,000 threshold: only for businesses based in one EU country, not the UK.
YesCheck the Article 59c conditions.NoThat threshold does not apply to you.Source 5
09Route chosen
Charge the right VAT, keep records, and file the matching return.
Marketplace first
If you sell through an electronic interface such as a marketplace, that interface may be treated as the deemed supplier for VAT.
Shipping from the UK
IOSS covers distance sales of goods imported from outside the EU in consignments not exceeding EUR 150. Sellers established outside the EU must appoint an intermediary to use the import scheme.
Over EUR 150
Above EUR 150 per consignment, IOSS does not apply. Follow the normal import VAT rules for the Member State of destination.
Goods already in the EU
If the goods already sit in the EU when you sell them, different rules apply, including intra-EU distance sales through the Union OSS or local VAT registration.
Northern Ireland
Sellers in Northern Ireland can register for the OSS Union scheme for distance sales of goods to EU consumers.
Common questions
Do Great Britain sellers need an intermediary for IOSS?
Yes. A taxable person established outside the EU must appoint an intermediary to use the import scheme.
Does IOSS cover alcohol or tobacco?
No. Products subject to excise duties cannot be declared in the import scheme.
Do UK sellers get the EUR 10,000 threshold?
No. Under Article 59c of the VAT Directive, the EUR 10,000 threshold only applies to businesses based in one EU country.
Is this tax advice?
No. It is general information from official pages checked on 9 November 2026. Rules change, so check the sources before you act.
Where the rules come from
- European Commission: Customs formalities for low value consignments checked 9 November 2026
- European Commission: One Stop Shop checked 9 November 2026
- European Commission: One Stop Shop: declare and pay checked 9 November 2026
- GOV.UK: Register to report and pay VAT on distance sales of goods from Northern Ireland to the EU checked 9 November 2026
- EUR-Lex: VAT Directive 2006/112/EC, Article 59c (consolidated 14 April 2025) checked 9 November 2026
This map is general information, not personal advice. Rules and rates change, so check the sources before you act. If your situation is tricky, talk to your accountant or tax adviser.